Market overview and structural significance of the Generative Artificial Intelligence (AI) Chipset Market
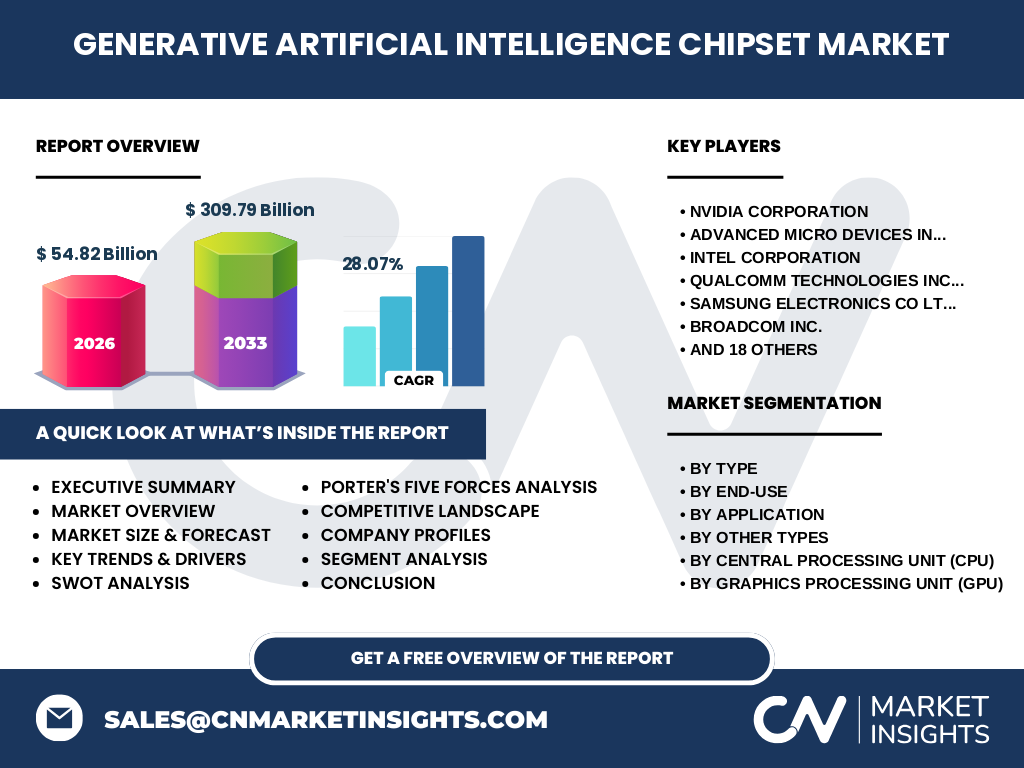
Our analysis indicates that the Generative Artificial Intelligence (AI) Chipset Market market size stands at 54.82 Billion in 2026. This foundational hardware layer powers large language models, multimodal content generation, and enterprise neural workloads, forming the backbone of the global digital infrastructure regulated by bodies like the European Union AI Office.
Structural Growth Drivers and Market Restraints
The Generative Artificial Intelligence (AI) Chipset Market industry trends are heavily accelerated by soaring enterprise demand for model optimization and fine-tuning. However, severe supply chain bottlenecks involving lithography equipment and rare earth raw materials like gallium act as major operational restraints for manufacturers shipping through key logistics hubs.
Emerging Technological Shifts
Based on our research, the market is undergoing a rapid transition toward specialized inference-optimized GPUs and domain-specific architectures. Innovators like Groq Inc. and Cerebras Systems Inc. are pioneering wafer-scale engines to bypass traditional von Neumann memory bottlenecks, shifting the competitive paradigm.
Pandemic Aftershocks and Recovery Trajectory
The COVID-19 pandemic severely disrupted semiconductor fabrication plants and packaging facilities across East Asia. The subsequent recovery trajectory shows robust resilience, with foundries accelerating automation and localized fabrication to mitigate future geopolitical shocks in the Generative Artificial Intelligence (AI) Chipset Market supply chain.
Competitive Benchmarking and Market Concentration
Market concentration remains high, dominated by hardware giants such as NVIDIA Corporation and Advanced Micro Devices Inc., alongside hyperscalers deploying custom ASICs. Meanwhile, agile challengers like Tenstorrent Inc. and SambaNova Systems Inc. carve out niches with highly adaptable, programmable computing fabric.
Executive Summary of High-Level Findings
The data suggests the Generative Artificial Intelligence (AI) Chipset Market analysis points to unprecedented expansion, driven by relentless breakthroughs in information cognition and large language model training. Enterprise adoption across BFSI and healthcare sectors underscores the critical strategic necessity of advanced silicon.
Long-Term Market Forecast through 2033
Projections reveal the Generative Artificial Intelligence (AI) Chipset Market will skyrocket to 309.79 Billion by 2033. Achieving a stellar 28.07% CAGR from 2027 to 2033, this trajectory reflects exponential enterprise scaling, massive data center overhauls, and widespread edge AI deployment.
Comprehensive Segmentation Breakdown
Our research segments the market by type into Central Processing Units (CPUs), Graphics Processing Units (GPUs), Field-Programmable Gate Arrays (FPGAs), and Application-Specific Integrated Circuits (ASICs). Application categories span text, image, and multimodal content generation, alongside dedicated LLM training and inference workflows.
Geographic Distribution and Regional Performance
Geographically, North America leads consumption due to hyperscale cloud providers, while Asia-Pacific dominates manufacturing through advanced foundries in Taiwan and South Korea. Regulatory compliance with agencies like the US Bureau of Industry and Security heavily dictates cross-border trade flows within the Generative Artificial Intelligence (AI) Chipset Market.
In-Depth Regional Market Review
Regional analysis highlights North America as the primary revenue generator for generative model optimization chips. Concurrently, the European market exhibits stringent compliance demands under the EU AI Act, favoring secure, energy-efficient edge processing solutions pioneered by firms like Hailo Technologies Ltd.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct competitive moats: Qualcomm Technologies Inc. and MediaTek Inc. target mobile edge intelligence, while Intel Corporation and Broadcom Inc. leverage expansive packaging ecosystems. Emerging players like Lightmatter Inc. introduce revolutionary optical interconnects to solve latency challenges.
Porter's Five Forces Industry Assessment
Supplier power in the Generative Artificial Intelligence (AI) Chipset Market remains exceptionally high due to extreme concentration in advanced node semiconductor fabrication. Conversely, competitive rivalry is fierce as fabless startups like Blaize Inc. and SiMa.ai Inc. challenge legacy architectures with proprietary inference engines.
SWOT Analysis of the Silicon Ecosystem
Strengths lie in massive parallel processing capabilities and surging software maturity. Weaknesses include high capital expenditure requirements for fabrication. Opportunities abound in automotive and industrial edge deployments, while threats stem from escalating geopolitical export controls and semiconductor nationalist policies.
Value Chain Flow from Raw Materials to End-Users
The value chain originates with polysilicon and chemical suppliers, progressing through advanced lithography equipment providers to pure-play foundries. Chips are then integrated by system vendors before deployment across key end-use verticals like banking, healthcare, and retail.
Strategic Investment Insights and High-Potential Areas
Investors should direct capital toward neuromorphic chips and optical computing startups like Esperanto Technologies Inc. and d-Matrix Inc. These technologies offer breakthrough power-efficiency ratios crucial for sustainable data center expansion and edge-based generative applications.
Conclusion and Strategic Takeaways
The Generative Artificial Intelligence (AI) Chipset Market represents a generational economic shift, validated by a robust 28.07% CAGR. Stakeholders must prioritize software-hardware co-design and resilient supply chain partnerships to capture value in this rapidly evolving landscape.
Proprietary Research Methodology
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-suite executives, exhaustive trade registry data from customs authorities, and secondary macroeconomic indicators regarding global semiconductor capital expenditures and fab utilization rates.
Scope, Parameters, and Report Limitations
This report covers worldwide revenue streams, shipments, and pricing dynamics for AI accelerators across designated types and end-use verticals from 2026 through 2033. Limitations include unforeseen macroeconomic shifts, trade tariff adjustments, and rapid technological obsolescence inherent to the semiconductor sector.
Recent Industry Developments and Strategic Moves
Recent market dynamism is marked by aggressive product launches and strategic alliances. Companies like Rambus Inc. and Lattice Semiconductor Corporation have introduced high-bandwidth memory interface solutions, while fabless innovators continuously secure funding rounds to accelerate commercial deployment of custom inference ASICs.